Rwanda produced 21,295 metric tons of green coffee in 2024/25 and exported 20,509 metric tons for $116.2 million, according to its National Agricultural Export Development Board (NAEB). Exports were up from 16,479 metric tons and $78.7 million a year earlier. About 400,000 smallholder families grow it, mostly Bourbon arabica, and fully washed coffee was 76.3% of 2023/24 exports.
The 2023/24 planted area was about 42,000 hectares (NAEB annual report 2023-2024); the 2024/25 figures are from NAEB’s agri-export performance report for 2024-2025. A quality problem specific to this part of East Africa is potato taste defect, a raw-potato smell traced to a single class of compound and covered further down.
Table of Contents
What Rwanda grows, in NAEB’s own words
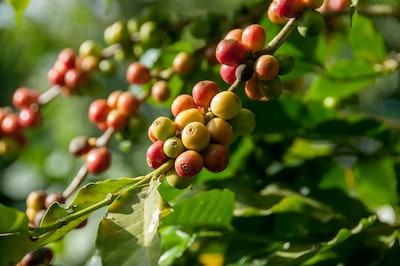
The board’s own description is short and worth quoting whole, because most of what circulates about Rwandan coffee is an elaboration on it: “Coffee was introduced by Germans in early 1900s, it is dominated by mainly ‘bourbon’ type of Arabica coffees.” It adds that “Currently, ca. 400,000 small holder farm families produce it and depend on it for their livelihoods”, and that “Coffee plays a major role in the economy of the country, contributing significantly to foreign exchange earnings and to the monetisation of the rural economy” (NAEB, Rwanda Coffee). The same page counts 79 coffee roasters and more than 117 exporters operating in the sector.
Bourbon is a variety group of Coffea arabica, not a species and not a processing method. NAEB says Bourbon dominates; it does not say Bourbon is all of it, and older Rwandan plantings include other arabica selections.
Is coffee Rwanda’s largest export?
Not usually. On NAEB’s numbers, which cover agricultural exports only, tea earned more than coffee in six of the eight years from 2017/18 to 2024/25; coffee came out ahead in 2022/23 and again in 2024/25:
| Financial year | Coffee export value | Tea export value |
|---|---|---|
| 2017/18 | $69,359,159 | $88,069,061 |
| 2018/19 | $68,763,924 | $83,552,108 |
| 2019/20 | $60.4 million | $93.6 million |
| 2020/21 | $61.5 million | $90.0 million |
| 2021/22 | $75.6 million | $103.5 million |
| 2022/23 | $115.9 million | $107.8 million |
| 2023/24 | $78,712,092 | $114.88 million |
| 2024/25 | $116,181,240 | $110,991,737 |
Figures from NAEB’s annual reports for 2018-2019 and 2023-2024, and its agri-export sector performance report for 2024-2025. The 2019/20 to 2022/23 rows are the bar labels of Figures 5 and 8 in the 2023-2024 report, which are in thousands of dollars, rounded here to $0.1 million. The 2023-2024 report gives the tea figure as a rise “from 93,559 million US $ in 2019-2020 to 114,882 million US $ in 2023-2024”; read against the dollar-level coffee figures in the same document, those are thousands, so $93.56 million and $114.88 million. For scale, NAEB puts Rwanda’s total agricultural export earnings for 2023/24 at $839,212,099, of which the traditional commodities — coffee, tea and pyrethrum together — accounted for $201,658,020, or 24 per cent. Coffee matters to Rwanda, and it matters most to the several hundred thousand households that grow it; it is not the country’s largest export line.
The washed-coffee rebuild, measured
The transformation people mean when they talk about Rwandan coffee is the shift from unsorted, sun-dried lots sold as bulk commodity to fully washed coffee processed at central washing stations. The most useful measure of how far that has gone is NAEB’s fully washed share. Its 2023/24 report prints two: 81.7% of production and 76.33% of the grades exported; a third, 78.3%, is in the PDF’s searchable text but covered on the printed page. All three say most of the crop is now fully washed; none says almost all. The exported share peaked at 82.93% in 2021/22, and NAEB notes “a continued tendency to produce more diversified coffee like natural coffee”.
The rest of the same year, from NAEB’s 2023-2024 annual report:
- Production: 17,038 MT, short of the 23,800 MT NAEB says it targeted (the same figure it gives as the export target).
- Exports: 16,479 MT, against a target of 23,800 MT.
- Revenue: $78,712,092, against a target of $87,150,000.
- Planted area: 42,429 hectares, which NAEB calls 105.5% of the 40,000 ha target (another panel on the same page gives 42,229 hectares, the figure that 105.5% fits).
- Yield: 2.6 kg per tree against a target of 4 kg, producing 71,958 MT of cherries, which NAEB scores at 65 per cent of target.
- Average price: $4.78/kg, down from $5.78/kg the previous year.
So in 2023/24 the land was planted and most processing had converted to washed; the constraint was productivity per tree. NAEB puts the production shortfall down to “limited applied fertilizer, climate stress, and ageing of the coffee trees”, and the year’s fall in agricultural export revenue partly to “reduced export volume in coffee”.
The next year turned the numbers around. For 2024/25 NAEB reports 21,295 MT produced against a plan of 21,386.9 MT, 20,509 MT exported, and revenue of $116,181,240 (NAEB, 2024-2025): up 47.6% on 2023/24, and about level with the $115.9 million of 2022/23.
Rwanda is a small origin by world standards. The USDA Foreign Agricultural Service coffee database puts the 2025/26 crop at 350 thousand 60-kilogram bags, all arabica — roughly a fifth of one per cent of world production, and about a twentieth of neighboring Uganda’s. USDA’s year for Rwanda runs April to March and NAEB’s July to June, so their year labels do not line up: NAEB’s 21,295 metric tons for 2024/25 is about 355,000 bags, close to USDA’s 350,000 for 2025/26. Everything Rwanda has done commercially follows from that: a country that cannot compete on volume competes on preparation.
The USDA figures above are from USDA’s July 2026 release; its next world coffee report is due on December 16, 2026.
Potato taste defect: what is established and what is not
This is the part of Rwandan coffee that most needs stating carefully, because the confident one-line version you will read elsewhere — “it is caused by the antestia bug” — runs ahead of the published evidence.
The compound is established. Cain and colleagues open their 2021 study: “The quality of East African coffee beans has been significantly reduced by a flavor defect known as potato taste defect (PTD) due to the presence of 2-isopropyl-3-methoxypyrazine (IPMP) and 2-isobutyl-3-methoxypyrazine (IBMP).” Testing roasted East African coffees classified as clean, mild, medium or strong PTD, they found that IPMP discriminated defective from non-defective samples while IBMP did not, and reported “a wide range of IPMP concentration (1.6-529.9 ng/g)” in defective samples against an average of 2.0 ng/g in clean ones (Cain et al., Journal of Agricultural and Food Chemistry 69(7): 2253-2261, 2021).
The antestia link is well supported. Jackels and colleagues describe PTD as “a flavor defect in East African coffee associated with Antestiopsis orbitalis feeding and… IPMP in the coffee”, and their gas chromatography work found the three most prevalent volatiles in desiccated antestia bugs — tridecane, dodecane and tetradecane — matching the surface volatile profile of defective coffee, with IPMP inside the bean. Their conclusion: “Coffee having visible insect damage exhibited both a PTD surface volatile profile and IPMP in interior volatiles, supporting the hypothesis linking antestia bug feeding activity with PTD profile compounds on the surface and IPMP in the interior of the beans” (Jackels et al., J. Agric. Food Chem. 62(42): 10222-9, 2014). Note the word: hypothesis.
The causal chain is not closed. A 2022 study from UC Riverside and National Taiwan University, working on raw beans from Rwanda specifically, states it plainly: “Although several causes for PTD have been proposed, none of them have been confirmed.” That team sequenced fungal communities in Rwandan beans scored for PTD and found six fungal sequence variants correlated with taste scores — four negatively, suggesting they may cause the defect, and two positively, suggesting they may suppress whatever does (Hale et al., Botanical Studies 63:17, 2022).
The bug itself is unquestionably a Rwandan problem. Researchers surveying Antestiopsis thunbergii — “a major coffee plant pest in Rwanda” — collected 154 individuals from eight localities in Rwanda for a study of its bacterial symbionts, published in Applied and Environmental Microbiology in 2014.
So the defensible summary is: a specific pyrazine produces the potato smell; antestia damage is strongly associated with beans that contain it; whether the bug introduces the compound, wounds the cherry so that something else produces it, or both, is not settled. Anyone who tells you it is settled is not reading the same papers.
Two practical consequences follow. The defect is a cup problem rather than a visual one — the concentrations above are nanograms per gram, and sorting by appearance will not reliably remove it — which is why Rwandan washing stations invest in pest control and hand sorting at the same time. And it is a reason to buy Rwandan coffee from roasters who cup their lots rather than from unbranded blends, since cupping is the detection method the research itself relies on.
Diseases, pests and price
Alongside antestia, the disease that dominates arabica everywhere it is grown is coffee leaf rust, and the rust risk rises steeply with temperature: controlled-environment work on three rust-susceptible arabica genotypes found sporulation of Hemileia vastatrix two thousand times higher under a 27-22 °C day/night regime than under 23-18 °C (Toniutti et al., Frontiers in Plant Science 2017). Our page on climate change and coffee farming sets out that finding and the wider modelling.
On price, Fairtrade International’s minimum for washed arabica is $1.80 a pound FOB, rising to $2.00 on 1 December 2026, with a $0.20 Premium and a $0.40 organic differential on top; the floor only bites when the market falls below it, and NAEB’s reported average of $4.78 per kilogram in 2023/24 is well above it. Rainforest Alliance certification sets no minimum price at all. Our page on fair trade versus organic coffee has the full table with the certifiers’ own documents cited.
For the two East African neighbours this origin is most often compared with, see Kenyan coffee, whose grading system is documented in detail by its own auction, and Ethiopian coffee, whose regional names are registered trademarks. For what happens to any of these beans after they leave the country, see coffee roast levels.
Corrections to earlier versions of this page
No flavour profile, no altitude band, no harvest-window precision beyond what NAEB publishes, and no assertion about blockchain traceability — the old version predicted it would be transformative and cited nothing. There is also no claim here about what proportion of Rwandan coffee is certified, because we did not find a figure in a source we opened.
Three citations pointed at a homepage. The page linked naeb.gov.rw three times — as the source for “Rwanda’s coffee export revenue was about $69 million in 2019”, for a claim about export demand, and for “Rwanda’s coffee exports generate over $60 million annually”. The NAEB home page carries no such figures. To be fair to the old page, the numbers themselves were close to right: NAEB’s own annual report for 2018-2019 records coffee export revenue of $68,763,924 that year and $69,359,159 the year before. The problem was that a reader following the link could not check them. Most figures on this page now point at the document that contains them.
- “The 1990s genocide” has been named. The event was the 1994 genocide against the Tutsi. A page that describes an industry rebuilt out of it can use the name.
- A “Rwandan Fair Trade Federation” was credited twice with promoting women’s participation and sustainable practices. We could not find an organisation of that name in any source we opened, including NAEB’s and Fairtrade International’s own sites, so it is not repeated here.
- The tasting notes are gone. “bright acidity, rich flavor, and subtle fruity undertones”, “fruity flavors that can range from red berries to citrus fruits” — nobody at this site has cupped a Rwandan coffee, and the page wrote as if somebody had. So is the altitude band of “1,500 to 2,000 meters”, which was stated twice with no source attached.
- The URL is misspelled and will stay that way. This page lives at
/rwandan-coffee-beans-history-rawanda/. Changing a URL breaks every link to it, so the misspelling stays.
Also corrected: an earlier version called coffee “Rwanda’s largest export”, twice; on NAEB’s numbers tea earned more than coffee in six of the eight years from 2017/18 to 2024/25. It said almost all Rwandan coffee is Bourbon, where NAEB says the crop is “dominated by mainly ‘bourbon’ type” arabica. It said fully washed coffee “accounted for 78.3%” of the crop; NAEB’s sentence does not say of what, and the same report prints two other shares for that year (81.7% of production and 76.33% of exported grades). And it devoted several sections to fair trade certification without saying what certification guarantees.